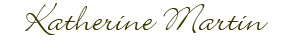
5 of Vancouver’s Most Popular Winter Activities
Katherine Martin • February 18, 2016

Skiing & Snowboarding (Not Included)

Do you live in or near Vancouver? Are you an outdoors lover, minus the whole skiing and snowboarding thing? Are you wondering how to spend your free time during the long, dreary winter months? Well, wonder no longer! The following are five non-skiing/snowboarding adventures that will get you outside and near (but not on) the slopes this winter…exactly where you want to be:

Ice skating (Robson Square)

Got the ice skating bug? If so, you have options. You could fire up your classic Nintendo and play some Blades of Steel (truly a classic of our time). Additionally, you could retrieve and play your copy of Blades of Glory, starring Will Ferrell. However, provided these excellent, albeit lazy, options don’t satisfy- if you simply must have the real thing, then look no further than the ice rink and plaza at Robson Square (sponsored and maintained by the Government of British Columbia).

This popular family attraction opens on December 1st of each year, and boasts extended holiday hours (closing for good at the end of February). Skating is free (which is a rarity these days) provided you bring your own skates. Otherwise the skate rental, with rental helmet included (safety first!), will set you back $4.00. A great deal by any standard.

This winter adventure, for which you don’t even need to leave the city, is fun for the whole family! It’s an afternoon complete with rosy cheeks, hot chocolate (fresh from the on-site concession stand) and a whole lot of laughs.

Snow Tubing (Grouse/Cypress/Whistler)

Rated a “2” out of “5” on the adventure scale, but a “5” out of “5” on the fun scale, we find snow tubing. This is a popular winter option across this great country of ours; however, the west, (according to many) does it best, with superbly maintained runs at some of the most well known mountains to grace the known landscape. Here are three options:

Squamish (Sea to Sky Gondola)
It’ll cost you five bucks to use the tubing hill in addition to $12 to $34 (depending on your age) for a gondola ticket, but the thrill is there, if you want it!

Cypress Mountain
Located a mere hop, skip and a jump from Vancouver proper, Cypress Mountain boasts six “tube shoots” from which to choose, varying in extremes from: your grandma’s tubing hill to “strap in and hold on tight”. The choice is truly yours.

Mount Seymour
The cost at this hill is a little steeper than the others (coming in at between $20 and $22 for two hours), but the fun, for many, is worth the price of admission. Also, Seymour includes a “tube tow”, so depending on who you are, an easy ride back to the top may very well be worth the extra few dollars. There is a sliding hill at this location as well, but this also costs a pretty penny- $10 is the standard rate, here, no time restrictions.

Snowshoeing

Continuing on our winter activities tour (minus the skiing and snowboarding), we come upon the sport (?) of snowshoeing. This is a touch more adventurous than snow tubing in addition to being a load more physically taxing, but the rewards: that of finding yourself in the great outdoors while clocking valuable exercise, are worth it to many snowshoe junkies. “Official” trails are available at most of the major ski hills (Cypress, Grouse, Seymour, Whistler, and Blackcomb) in addition to free trails in and throughout the lower mainland.

Cross Country Skiing (Cypress/Whistler’s Olympic Park)

Combine the physicality of snowshoeing with a heightened level of skill, and what do you get? That’s right…cross country skiing. Of note here, Cypress Mountain includes several kilometres of groomed trails complete with stunning views of the surrounding landscape, and delicious meals at their lodge. Additionally, if you don’t mind driving the extra distance, Whistler’s Olympic Park is a state of the art, cross country skiing heaven.

Visit Vancouver Island

Finally, I’d be remissed if I didn’t mention the beauty that is Vancouver Island. When the January/February doldrums hit, what better than cross the channel into green grass, rain forests, surfing and hiking. BC Ferries terminals in Tsawwassen and Departure Bay give quick access to this mid-winter hideaway. It’s like winter never existed.
Katherine Martin


Origin Mortgages

Phone: 1-604-454-0843
Email: 
kmartin@planmymortgage.ca
Fax: 1-604-454-0842

RECENT POSTS
By Katherine Martin • September 30, 2026
Mortgage Options During Divorce or Separation: What You Should Know If you’re going through—or considering—a divorce or separation, you may not realize that there are mortgage solutions specifically designed to help one party keep the home . For many people, the family home is their largest asset and where most of their equity is tied up. In situations like this, a spousal buyout program can allow one person to refinance the property and buy out the other party’s share—often up to 95% of the home’s value . This option can work whether you want to keep the home or your former partner does. What Is the Spousal Buyout Program? The spousal buyout program is a refinancing option that allows one owner to purchase the other owner’s share of the property as part of a separation or divorce settlement. In some cases, it can also be used to pay off jointly held debts, as outlined in a legal agreement. Below are some of the most common questions about how the program works. Is a finalized separation agreement required? Yes. Lenders require a signed and finalized separation agreement that clearly outlines how assets and debts are to be divided. This document is essential for approval. Can the funds be used for renovations or personal debts? No. Funds from a spousal buyout can only be used to: Buy out the other owner’s share of equity Pay off joint debts specifically listed in the separation agreement They cannot be used for renovations, personal loans, or unrelated expenses. How much equity can be accessed? The maximum amount available is the amount required to: Buy out the other party’s agreed-upon share of equity Pay off any joint debts listed in the agreement This amount cannot exceed 95% loan-to-value . What is the maximum loan-to-value allowed? The maximum loan-to-value is the lesser of : 95%, or The remaining mortgage balance plus the required buyout and joint debt payout The property must be the primary owner-occupied residence . Do all parties need to be on title? Yes. All individuals involved in the buyout must currently be registered on title. Your solicitor will confirm this through a title search. Does this only apply to married or common-law couples? No. While commonly used for married or common-law couples, the program may also apply to siblings or friends who jointly own a property and need one party to exit the mortgage. These cases are typically reviewed on an exception basis and require insurer approval. If no separation agreement exists, the purchase contract must clearly outline the buyout terms. Is a full appraisal required? Yes. A physical, on-site appraisal is required to confirm the property’s value before the mortgage can be finalized. Final Thoughts This overview covers some of the most common questions about mortgage options during separation or divorce, but every situation is different. Working with an independent mortgage professional gives you access to multiple lenders, specialized programs, and unbiased advice—so you can clearly understand your options and choose what’s best for your future. If you’re navigating a separation and need guidance around keeping or selling the home, feel free to connect anytime. All conversations are handled with discretion and confidentiality, and I’d be happy to walk you through your options.
By Katherine Martin • September 23, 2026
Why More Mortgage Options Matter—Especially for Assignment Purchases One of the biggest advantages of working with an independent mortgage professional is access to choice. Instead of being limited to one lender and one set of products, mortgage brokers work with multiple lenders—each with different guidelines, risk tolerances, and mortgage solutions. That flexibility becomes especially valuable when your situation doesn’t fit neatly into a “standard” box. A great example of this is purchasing new construction through an assignment contract . Why Assignment Purchases Can Be Challenging Assignment purchases are often viewed as higher risk by traditional lenders. Rather than declining these deals outright, many lenders quietly make them difficult by adding layers of conditions, restrictions, or uncertainty. This can lead to delays, frustration, or financing falling apart late in the process. The Good News There are lenders—available exclusively through the broker channel —that have clear, favourable policies for assignment purchases. With the right lender and proper planning, these transactions are absolutely doable. Typical Financing Requirements for Assignment Purchases While every situation is unique, many lenders that allow assignment financing look for the following: Standard purchase qualification, including income verification, credit, and down payment Assignments accepted at either the original purchase price or current market value Minimum 620 credit score , with no prior bankruptcies or consumer proposals The full down payment must come from the purchaser —seller incentives cannot be used Required Documentation To secure financing, lenders typically require: The original purchase agreement signed by all parties The MLS listing (if applicable) The assignment agreement signed by the builder, original purchaser, and new buyer Any side agreements outlining changes to the purchase price A full appraisal to confirm value This list isn’t exhaustive, but it highlights that while assignment purchases require more coordination, they are very achievable with the right lender and guidance. Final Thoughts Assignment contracts can open doors to great opportunities—but only if your financing supports the transaction. This is where access to multiple lenders and specialized policies makes a real difference. If you’re considering purchasing new construction through an assignment, or if you’d like to explore more traditional purchase options, feel free to connect anytime. I’d be happy to walk you through the mortgage products available and help you choose an option that doesn’t limit your financing possibilities.