How To Save $1 Million For Retirement
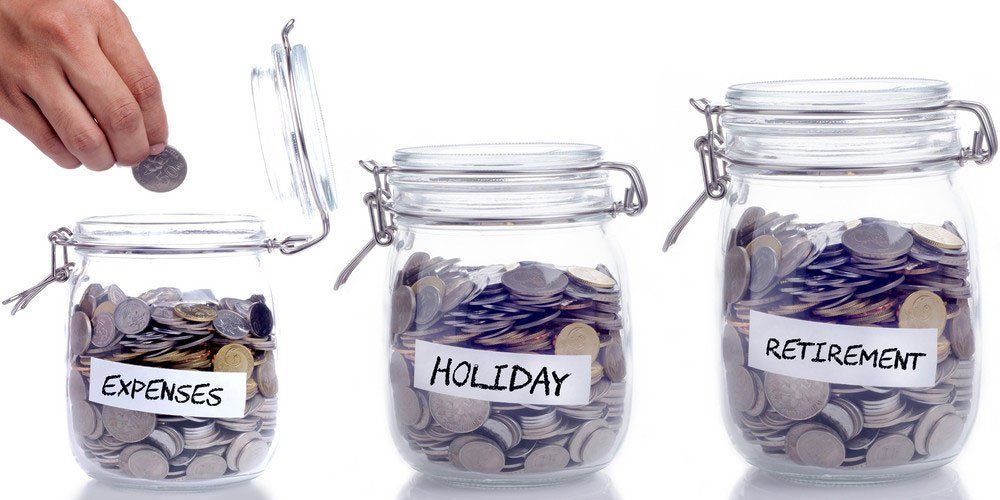
Starting to save early for retirement is extremely beneficial in the long run, especially if you have the dream of retiring with $1 million as so many Canadians do. It’s not an easy feat, but for most Canadians, retiring with $1 million is a realistic goal. You most likely won’t be flying private or have a butler, but retiring with $1 million means you can live comfortably (especially if you follow the 4% rule, which suggests withdrawing no more than 4% of your nest egg each year to maintain the principle, if you factor in interest rates and inflation).
So how can you actually save a million dollars? Discipline and planning will help you pave the way to seven figures by retirement. Here are 8 tips to help get you there:
1. Save early
Let’s say you’re 25, you have no real savings, your annual earned income is $40,000, and you plan to retire in 40 years. In order to retire with $1 million, you must save $502.14 each month for 40 years at a 6% rate of return.
Now let’s say you wait until you’re 45 to start saving (maybe paying off debt has held you back), and at this point you have no real savings, your annual earned income is $72,000, and you plan to retire in 20 years. In order to retire with $1 million, you must save $2164.31 each month at a 6% rate of return.
What to take away from this: It’s never too late to start saving, however, building wealth later in life or in the last decade before you retire can be really hard. To live well when you’re old means you should start to save while you’re young. Most millionaires in retirement that I know developed good spending, saving, and investing habits when they were young. Also, starting earlier gives your money more time to grow through compounding interest. Saving thousands a month right now may seem (or be) impossible, but you’re better tp start saving something.
2. Pay yourself regularly
Setting up automatic withdrawals (or “payments to yourself” as I like to look at them) from your checking account to your savings (or RRSP) is a great way to build wealth. It may be an adjustment at first (since you’re used to having that “extra” income), but you’ll get used to it pretty fast. You’ll also feel great knowing you haven’t dipped into cash you “should be” saving, and soon enough you won’t even miss the money.
What to take away from this: You’re doing something really good for yourself (and future you) by setting up automatic payments ! Saving should be habitual and easy, so don’t make it painful or harder than it has to be.
3. Live within your means
This one shouldn’t come as a surprise to you! I’ve talked about living within your means before, and how you should avoid the pressure to spend and keeping up with the Joneses.
To know if you’re living above your means, answer this one question: do you carry a credit card balance that you’re having trouble paying off in full? If you answered yes, please read on.
You don’t need the biggest home or newest car (and anyone who makes you feel that way need not be in your life). Simply establish a comfortable standard of living you can maintain. Save at least 10% of your paycheque and save your bonuses (and raises) instead of spending them. If you live within your means you won’t need to dip into your reserve funds, and you can actually watch your savings grow.
What to take away from this: Earn more money, or spend less of what you earn (the latter is much easier to do).
4. Manage debt

Credit cards, lines of credit, loans, and any other debt you can think of should be managed and paid off ASAP, otherwise you risk throwing away thousands of dollars in interest each year. Even if you have to stop saving for a year or two, do it!
Oh, and maybe before you lay down the plastic again, ask yourself if you have enough cash in your checking account to cover the purchase. If the answer is no, ask yourself why you’re spending money you don’t have.
What to take away from this: Pay off your debt as quickly as possible (high interest debt first) and be responsible with your credit card(s).
5. Don’t splurge too soon
While a home may appreciate in value and help you eventually build wealth, a car depreciates the second you take it out of the lot, so consider where you’re making your big purchases. If you can afford the monthly payments on your leased Audi, great! But, if your monthly car payments are higher than your monthly RRSP contributions (or other savings), you need to reassess what you’re doing.
A new job or pay increase can be exciting and trigger a desire to upgrade, but rather than going out and buying the most expensive sports car in the lot, or the biggest house on the block (hello, house poor!) consider an option that’s somewhere between what you have now and what your dream is.
What to take away from this: Splurging too soon may throw you into debt you don’t want to be in. Also, buying top-of-the-line items right away leaves little to look forward to the next time you make a similar purchase. Spend your money thoughtfully.
6. Be frugal
Being frugal doesn’t mean you’re cheap – there is a difference! Prioritize your spending so you can have more of the things or experiences you really want. Let’s say it’s your partner’s birthday. A frugal person would probably have made dinner reservations, since it’s an occasion to celebrate. A cheap person won’t make reservations and may not even make dinner at home.
Indulging is okay; we all need it at times. But affordable indulgences are what you should be after (example: barbecue a surf n’ turf dinner at home instead of going to a pricey steakhouse). Make sure you’re spending within the lines.
What to take away from this : Understand that paying more doesn’t necessarily mean you’re getting better value.
7. Invest

“How many millionaires do you know who have become wealthy by investing in savings accounts? I rest my case.” – Robert G. Allen
According to a study by Statistics Canada , 31% of those surveyed betweem ages 45 and 60 said their financial preparations for retirement were insufficient. Further, a study by RBC revealed 56% of non-retired Canadians were worried they wouldn’t be able to enjoy the life in which they are currently accustomed to.
Investing is one of the most powerful tools to grow your wealth. Putting all your savings into a bank account that returns 1% is not the way to grow your wealth quickly. Investing your money provides larger returns and means you could have multiple income sources, helping you rest easier in retirement.
Make sure to watch out for high and hidden fees , as they can eat away at your investments’ potential growth. Plenty of low-cost solutions for investors are popping up, and fee based advisors, like some robo-advisors , can offer unbiased investment advice, as well as help you set realistic financial goals that match your life goals.
What to take away from this: Put your money to work for you , and you eventually won’t have to work so hard for it.
8. Re-evaluate
Life changes, so don’t expect everything to go according to plan. It’s easy to say you’ll save 10% or 15% of each paycheque, but the reality is, it’s not so easy!
Inflation, income changes, emergencies, employment changes, life expectancy, and priorities ( ever had a baby? It’s expensive, and wonderful!) in general can affect our financial plans. When it comes to saving, it’s always better to save more than to be sorry you didn’t.
What to take away from this: Stick to the fundamentals, and adapt as your life changes.
Retiring with $1 million doesn’t have to be a dream if you plan for it. Use my tips as guidance, and you could make your dream a reality.
Try out this Million Dollar Savings Calculator to see how much you should start saving each month to retire as a millionaire.
This article was written by Randy Cass, and was originally published here on June 8, 2016.
Katherine Martin
Origin Mortgages
Phone: 1-604-454-0843
Email: kmartin@planmymortgage.ca
Fax: 1-604-454-0842
RECENT POSTS